
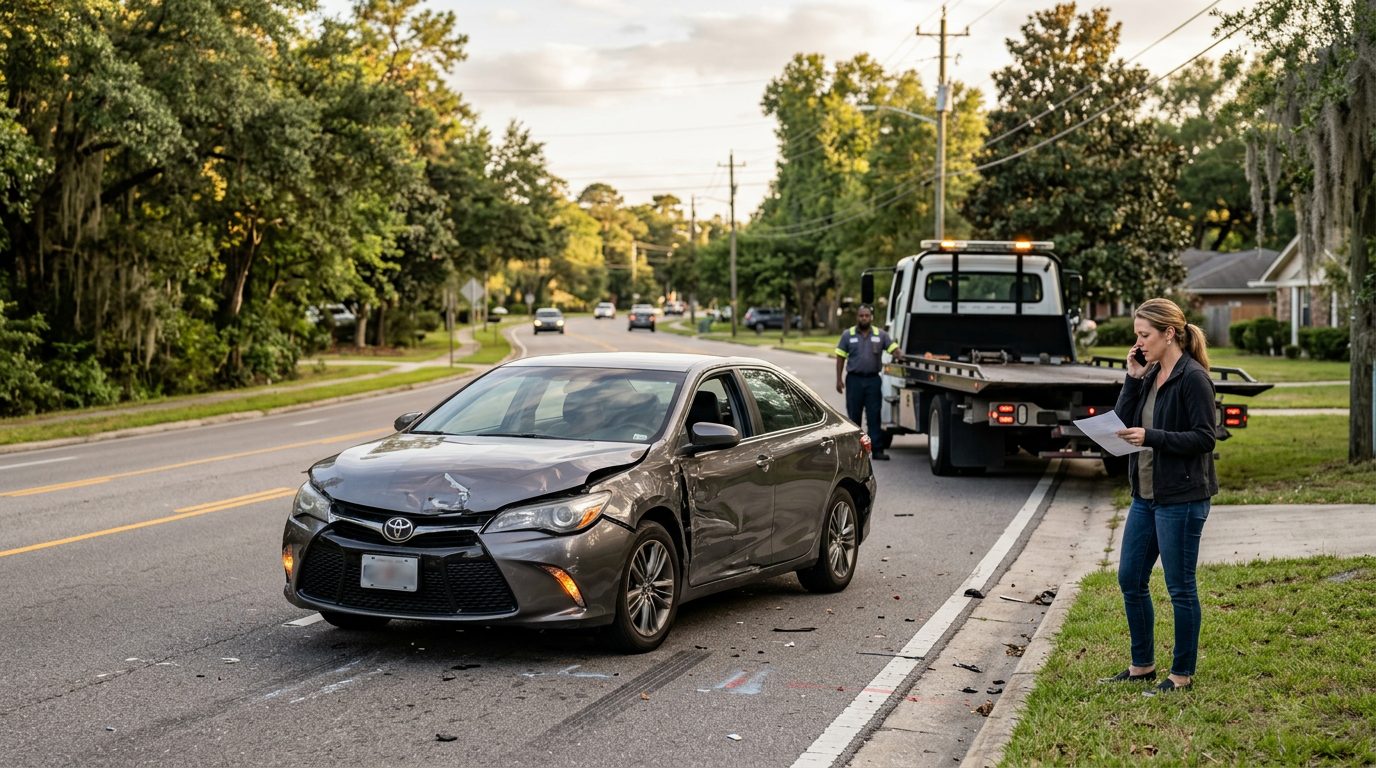
Uninsured Motorist Car Accidents · New Orleans, Louisiana
Hit by an Uninsured Driver? Talk With a New Orleans Trial Lawyer About Your Options
Przemek Lubecki and our team at American Trial Lawyer represent people seriously hurt in car accidents in Orleans Parish, the New Orleans metro and across Louisiana. Your first consultation is free, confidential and comes with no obligation to continue. You may be responsible for case costs and expenses in addition to any fee.
By Przemek Lubecki · Published October 21, 2026
If the driver who hurt you had no auto insurance, or not enough to cover your losses, your own policy may help. In Louisiana, that protection is called uninsured motorist (UM) coverage, and it can also apply when the other driver is underinsured (UIM). This page explains how the coverage works, what an uninsured motorist car accident claim in Louisiana involves, and how American Trial Lawyer approaches these cases.
What uninsured and underinsured motorist coverage is
Uninsured motorist (UM) coverage is part of your own auto policy. It pays when the at-fault driver has no liability insurance. Underinsured motorist (UIM) coverage applies when the other driver’s insurance is too small to cover your losses.
La. R.S. 22:1295 sets the rules for this coverage. Louisiana auto liability policies must include UM coverage unless the named insured rejects it, selects lower limits, or selects economic-only coverage, in the way the statute describes.
The coverage comes from your policy, not the other driver’s. Which policy applies depends on the facts of your case and the terms of the coverage involved. Who counts as insured depends on the wording of the policy, so read who is named in it.
If you choose to move forward, we discuss how the firm works, including that you may be responsible for case costs and expenses in addition to any fee. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Who this claim is for
This claim fits people hurt in a crash with a driver who had no insurance or too little. It may also fit these readers:
- Drivers and passengers injured by an uninsured or underinsured driver.
- Pedestrians and cyclists hit by a motor vehicle. Whether they are covered depends on the policy’s terms.
- Families of someone killed in such a crash. Louisiana lets certain relatives bring a wrongful death action. The spouse and children come first. If there is no spouse or child, the parents may sue. Then come siblings and grandparents, in that order. La. Civ. Code art. 2315.2 sets this order.
- Anyone unsure whether their policy includes UM or UIM coverage, or which limits they chose.
A wrongful death claim is separate from any claim the injured person could have made. The deadlines can differ, so early action protects your options.
What a UM or UIM claim can cover
A UM or UIM claim seeks the damages your policy covers. The policy’s limits cap what it pays.
- Economic loss. These are money losses you can count, such as medical bills and lost pay.
- Noneconomic loss. Pain, suffering, inconvenience and mental anguish fall here. An economic-only policy leaves these out.
- Medical bills. When a health insurer or Medicare paid a contracted provider, recovery is limited to the amount actually paid, plus cost sharing you owe. It is not the amount billed. See La. R.S. 9:2800.27.
- See La. R.S. 22:1295.
- Punitive damages. The policy may exclude punitive or exemplary damages.
Read your own policy language. The exact terms decide what applies to your crash.
How a UM or UIM claim works, step by step
A UM or UIM claim usually moves through medical care, records, notice to your insurer, proof of coverage, and a negotiated claim. A lawsuit follows if the claim cannot be resolved.
- Get medical care and keep records. Save every visit note, bill and prescription receipt.
- Report the crash and gather facts. Call the police. Collect the other driver’s details, witness names, and photos of the scene and vehicles.
- Tell your own insurer. Report the crash to the insurer that issued your policy soon after it happens.
- Document the other driver’s coverage. Ask for proof of the other driver’s insurance and limits. Keep any denial letter.
- Present the claim. Insurers may make offers below what your losses are worth. You don’t have to accept an offer.
- Watch the deadlines. Under La. R.S. 9:5629, a claim under UM policy provisions prescribes two years from the accident. The Louisiana State Bar Association prescription card lists this deadline. Under La. Civ. Code art. 3493.1, delictual (tort) actions generally run two years from the day injury or damage is sustained. The exact date depends on the facts.
Common questions about these claims
Most questions come down to fault, deadlines and what your policy says.
Can I still recover if I was partly at fault?
Under La. Civ. Code art. 2323, a person whose negligence is equal to or greater than fifty-one percent of the fault is not entitled to recover damages. Under La. Civ. Code art. 2323, if the negligence attributable to the person suffering injury is less than fifty-one percent, the damages recoverable are reduced in proportion to that degree of negligence. See La. Civ. Code art. 2323.
Can I reject UM coverage?
The UM requirement does not apply if a named insured rejects coverage, selects lower limits, or selects economic-only coverage, as the statute provides. See La. R.S. 22:1295.
What if the insurer offers a low amount?
You don’t have to accept an offer. Ask how the insurer figured it, and keep every letter.
Will I need to go to court?
Some claims resolve without a lawsuit. Others need one. Filing deadlines still apply either way.
How American Trial Lawyer approaches these claims
American Trial Lawyer represents people seriously hurt in truck, commercial vehicle and car crashes, and families in wrongful death cases. The firm’s office is in New Orleans, Louisiana. Przemek Lubecki, a trial lawyer, is the responsible lawyer for this page’s content.
The firm serves people across Orleans Parish, the New Orleans metro and Louisiana. That includes readers in Jefferson Parish, Metairie, Kenner, St. Bernard Parish and Slidell.
For a UM or UIM matter, the work often includes:
- Reviewing your own policy, including UM and UIM limits and any other policies that may apply.
- Organizing medical records, bills and proof of your losses.
- Communicating with insurers on your behalf.
The firm may associate or refer a case to other law firms.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Next steps: request a free case evaluation
If the other driver had no insurance or too little, you may have a claim. You don’t have to sort out the next steps alone.
Our team can review your crash, your policy and your medical bills. The first consultation is free, confidential, and without obligation to continue. You may be responsible for case costs and expenses in addition to the fee.
Request a free case evaluation or call 855-LUBECKI (Office in New Orleans).
How We Can Help With an Uninsured Motorist Claim
Looking at every available source of recovery
When the at-fault driver has no insurance, we review the other coverage that may apply to your injuries and losses, including your own policy.
Organizing the proof
We help gather crash reports, medical records, bills, photos and witness information so your claim is documented from the start.
Straightforward communication
We explain each step in plain language, so you know what is happening with your claim and why.
Attention to the whole picture
Your recovery comes first. We take the time to understand how the crash has affected your health, work and family.
A Quick Tip After a Crash
Keep every record you can: the crash report number, photos of the scene and vehicles, names of any witnesses, and all medical visits and bills. Before you give a recorded statement or sign anything from an insurance company, consider speaking with a lawyer first.
What to Expect When You Reach Out
1. Tell us what happened
Share the basics of the crash and your injuries during a free, confidential first consultation. There is no obligation to continue.
2. We review your situation
Przemek Lubecki reviews the facts, the available insurance and your medical needs, and explains the options under Louisiana law.
3. You decide the next step
If you choose to move forward, we discuss how the firm works, including that you may be responsible for case costs and expenses in addition to any fee.
Working with other firms
The firm may associate or refer a case to other law firms. If that happens, we will tell you clearly and explain how the representation will be handled.
Injured by an Uninsured Driver? Start With a Free Consultation.
Related practice areas
- Do I Need a Lawyer After a Car Accident in New Orleans? Questions to Answer Before You Call
- Semi Truck Crash I-10 New Orleans Claim Guide