
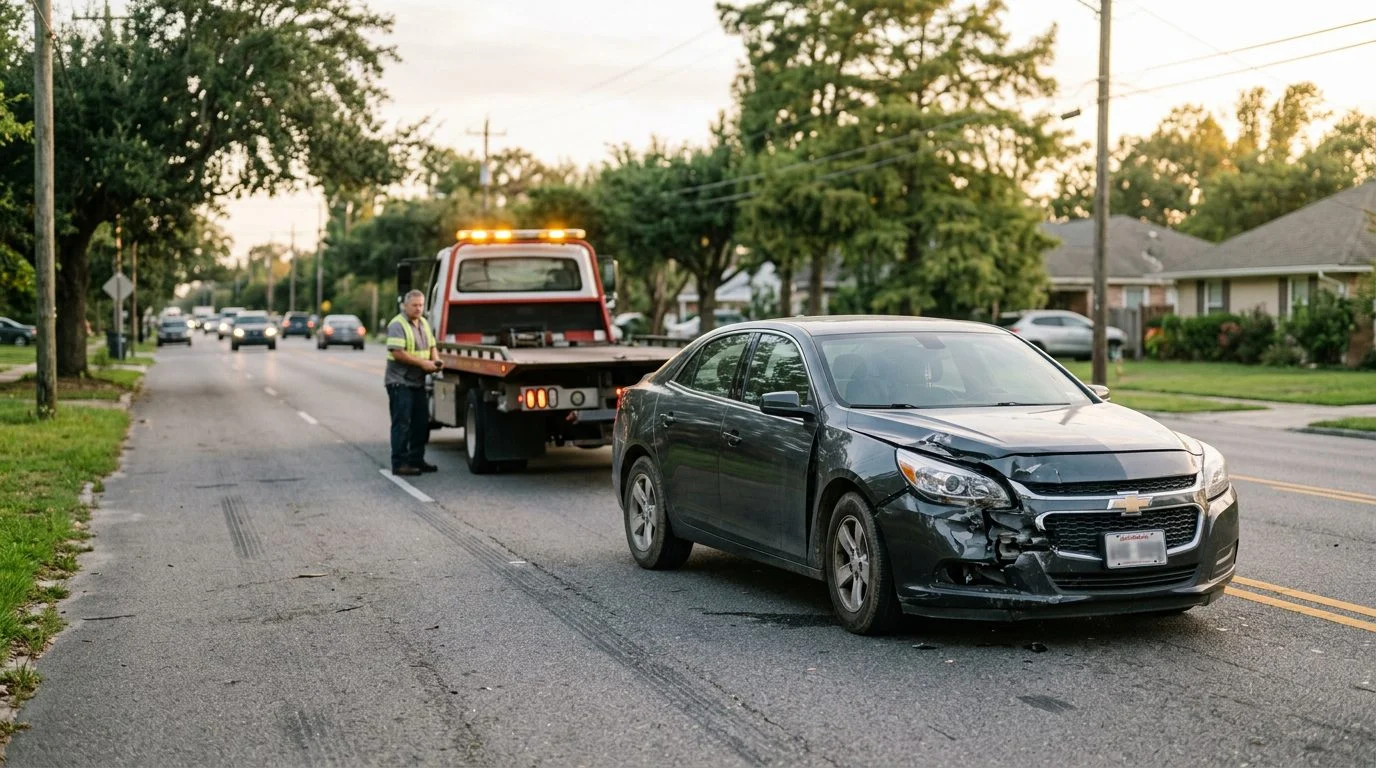
New Orleans car crash claims | Underinsured motorist coverage
Hurt in a New Orleans crash? Understand the coverage that may apply to your claim.
When the at-fault driver carries too little insurance, your own policy can matter. Here is how to think through that question, and how to talk with a trial lawyer about it.
By Przemek Lubecki · Published November 9, 2026
Underinsured motorist coverage can help pay your losses after a Louisiana car crash when the at-fault driver’s insurance is not enough. It is part of your own auto policy. This guide explains how it works, how it differs from uninsured coverage, and what choices you may have made when you bought your policy. It also covers practical steps and deadlines for crashes in New Orleans and across Louisiana.
What Underinsured Motorist Coverage Is and How It Differs from Uninsured Coverage
Underinsured motorist (UIM) coverage is part of your own auto policy unless the named insured rejects coverage, selects lower limits, or selects economic-only coverage. It may pay when the at-fault driver’s liability limits are too low to cover your losses.
Louisiana’s uninsured motorist law protects people insured under a policy who can legally recover nonpunitive damages from the owner or operator of an uninsured or underinsured vehicle, unless the named insured has rejected the coverage, selected lower limits, or selected economic-only coverage. The recovery must be because of bodily injury, sickness, or disease, including death. La. R.S. 22:1295
Uninsured motorist (UM) coverage protects you when the at-fault driver’s vehicle is uninsured or underinsured. La. R.S. 22:1295 reads: “(f) Uninsured motorist coverage shall include coverage for bodily injury arising out of a motor vehicle accident caused by an automobile which has no physical contact with the injured party or with a vehicle which the injured party is occupying at the time of the accident, provided that the injured party bears the burden of proving, by an independent and disinterested witness, that the injury was the result of the actions of the driver of another vehicle whose identity is unknown or who is uninsured or underinsured.” UIM applies when that driver has some insurance, but not enough. Often both coverages appear on the same policy, so people mix them up.
A UIM claim usually starts with the at-fault driver’s liability limits.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Louisiana Minimum Liability Limits Create the Coverage Gap
The gap appears when the at-fault driver’s bodily injury limit is lower than your losses.
Louisiana motor vehicle liability policies come from insurers authorized to do business in the state. Their limits are set by statute. La. R.S. 32:900 Bodily injury liability pays for injuries to other people. Property damage liability pays for damage to property, such as a car or a fence. Property damage limits do not set how much you can recover for your own injuries.
Here is a simple example. Say your emergency care, surgery, and months of missed work add up to more than the other driver’s bodily injury limit. The amount above that limit is the gap. Your own UIM coverage may help address it, if you carry that coverage. Pain and suffering can add to the total, too.
Motor carriers operating a vehicle with a gross vehicle weight or gross combined weight rating over twenty thousand pounds carry higher required limits, with exceptions for certain tow trucks, farm vehicles, and forest-product vehicles. Under La. R.S. 32:900, vehicles with a gross vehicle weight of more than fifty thousand pounds must provide liability coverage of at least three hundred thousand dollars per occurrence. The insurer may instead provide one hundred thousand dollars for injury or death to any one person, with at least three hundred thousand dollars per occurrence, plus twenty-five thousand dollars for property damage. La. R.S. 32:900 Higher limits do not end the question, though. How large any gap is turns on the injuries, the treatment, and the facts of the crash.
Can You Reject Uninsured or Underinsured Motorist Coverage in Louisiana?
Yes. La. R.S. 22:1295
Economic-only coverage works differently. Insurers may offer it at a reduced premium with an exclusion for all noneconomic loss. The statute defines noneconomic loss as any loss other than economic loss, and includes but is not limited to pain, suffering, inconvenience, mental anguish, and other noneconomic damages otherwise recoverable under the laws of this state.
Each choice has a tradeoff. If the named insured rejects coverage or picks lower limits on the commissioner’s prescribed form, signed by the named insured or a legal representative, that coverage does not apply at the level chosen. The statute also says a renewal does not have to offer the coverage again when the named insured rejected it or chose lower limits before, with the same insurer or its affiliates.
Your declarations page shows the limits on your policy. Compare those limits with the choices you remember making. Then think about how a serious injury would affect your bills and income. Whether a particular choice fits your situation depends on the facts.
How an Underinsured Motorist Claim Typically Works
A UIM claim usually moves in stages. It starts with notice to your own insurer, then proof of your losses, then a response from the at-fault driver’s liability insurer.
Many UIM policies require notice to your own insurer before you accept the other driver’s liability limits. The exact requirement comes from your policy language, so it is worth raising with your insurer early.
Good documentation supports a claim. Gather medical records and bills, wage records showing time missed, the crash report, photos of the vehicles and scene, and names of any witnesses.
Some UIM claims settle through negotiation. Others may need a lawsuit. Outcomes differ from case to case, and no one can predict how a particular claim will end.
When the Other Driver Had No Insurance
If the other driver had no liability insurance, the question becomes whether you carry UM coverage for the loss.
Write down what you know about the other driver while it’s fresh. Keep their name, address, plate number, and any statement they make at the scene. These details help identify the vehicle and its owner.
Steps to Take After a Crash With an Uninsured or Underinsured Driver
The first steps are medical care, the police report, and notice to your own insurer.
Get medical care promptly, even when your injuries seem minor. Keep every appointment and save every bill. These records shape any claim.
Report the crash to police. Louisiana law requires the investigating officer to tell each driver to report certain information to anyone hurt or with property damage from the crash. La. R.S. 32:398 requires a driver involved in a crash resulting in injury or death, or property damage in excess of five hundred dollars, to give their own name, address, and vehicle registration number to anyone injured or whose property was damaged, and to exhibit their license on request if available. Collect the other driver’s name, license, plate, and insurance details if you can do so safely.
Request the crash report. Under the statute, reports are confidential, but upon request they are available within seven working days after the investigation is completed to the parties to the crash, parents or guardians of a minor party, the parties’ insurers or an insurance support organization under contract with them, healthcare providers who treated a party, the parties’ succession representatives, the attorneys of the parties or succession representatives, and news-gathering organizations requesting documents on a specific crash. Copy fees are capped at five dollars for reports of two pages or less, and twenty dollars for longer reports. La. R.S. 32:398
Notify your own insurer of the crash and your injuries. Keep a written log of every call and letter. Track time missed from work and the daily limits your injury places on you.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Damages and Deadlines Affect a UIM Claim
For most injury claims, Louisiana sets a two-year liberative prescription (filing deadline). It runs from the day the injury or damage is sustained. La. Civ. Code art. 3493.1 Actions for damages under the uninsured motorist provisions of a policy are prescribed by two years from the date of the accident. La. R.S. 9:5629
Fault matters too. La. Civ. Code art. 2323 That current text took effect January 1, 2026, so the crash date matters.
Damages commonly include medical bills, lost wages, and noneconomic losses such as pain and suffering. The Louisiana State Bar Association consumer brochure explains that lost wages may be part of damages. It also says UM and UIM coverage may pay medical bills and lost wages. Economic-only coverage leaves out noneconomic loss.
Frequently Asked Questions
Underinsured coverage applies when that insurance is too low for your losses.
Does Louisiana require car insurance?
Yes. Under La. R.S. 32:861, a registered self-propelled vehicle must be covered by an automobile liability policy or another form of security the statute allows, except those motor vehicles used as agricultural or forest vehicles during seasons when they are not used on the highway, those used primarily for exhibit or kept primarily for use in parades, exhibits, or shows, and lease-bound mobile rig haulers as defined in Subsection D of this Section.
Can lost wages be part of a claim?
Yes. The Louisiana State Bar Association consumer brochure says lost wages may be part of damages from a Louisiana auto accident.
Talk With American Trial Lawyer About Your Crash and Your Coverage
If the other driver’s limits may not cover your medical bills and lost wages, you may be asking what your own UIM coverage can pay.
A serious injury brings bills, missed paychecks, and hard questions about insurance, all at once. Talking through the coverage on your policy can help you see your options.
American Trial Lawyer, LLC is a personal injury trial law firm with its office in New Orleans, Louisiana. Przemek Lubecki is the responsible lawyer for this page. The firm handles truck accidents, car accidents, commercial vehicle accidents, rideshare accidents, motorcycle accidents, wrongful death, brain injury, and negligent security matters.
The firm may associate or refer a case to other law firms. Any co-counsel is a separate firm and is not part of American Trial Lawyer, LLC. Przemek Lubecki is licensed to practice law in Louisiana.
If your injuries and bills may be larger than the other driver’s insurance, the first consultation is free, confidential, and without obligation to continue. Call 855-LUBECKI (Office in New Orleans) or request a free case evaluation. No outcome can be promised.
Attorney advertising.
Why talk with American Trial Lawyer
Trial lawyer in charge
Przemek Lubecki is the responsible lawyer for this page and for the firm's car crash matters. He handles cases in New Orleans and across Louisiana.
Office in New Orleans
Our New Orleans office serves Orleans Parish, the New Orleans metro, Jefferson Parish, St. Bernard Parish and the rest of Louisiana.
Plain-language answers
We explain your policy, your options and the next steps in terms you can follow, without pressure.
Free, confidential first consultation
Your first consultation is free, confidential and carries no obligation to continue.
Keep your information ready
Before you speak with any insurance company about your crash, gather the other driver's insurance details, the police report number, and a copy of your own auto policy.写 down what you remember while it is fresh.
Questions to bring to your consultation
What does my policy say?
Bring your declarations page and any endorsements so we can review the uninsured and underinsured motorist limits together.
What coverage did the other driver carry?
Ask the other driver's insurer for the policy limits and confirm whether the coverage was in force at the time of the crash.
What are my medical and wage losses?
Keep every bill, record and note about missed work. These details help show the full impact of the crash.
Who else may be responsible?
Crashes involving commercial vehicles, rideshare drivers or employers can involve more than one insurer. We look at every possible source of coverage.