
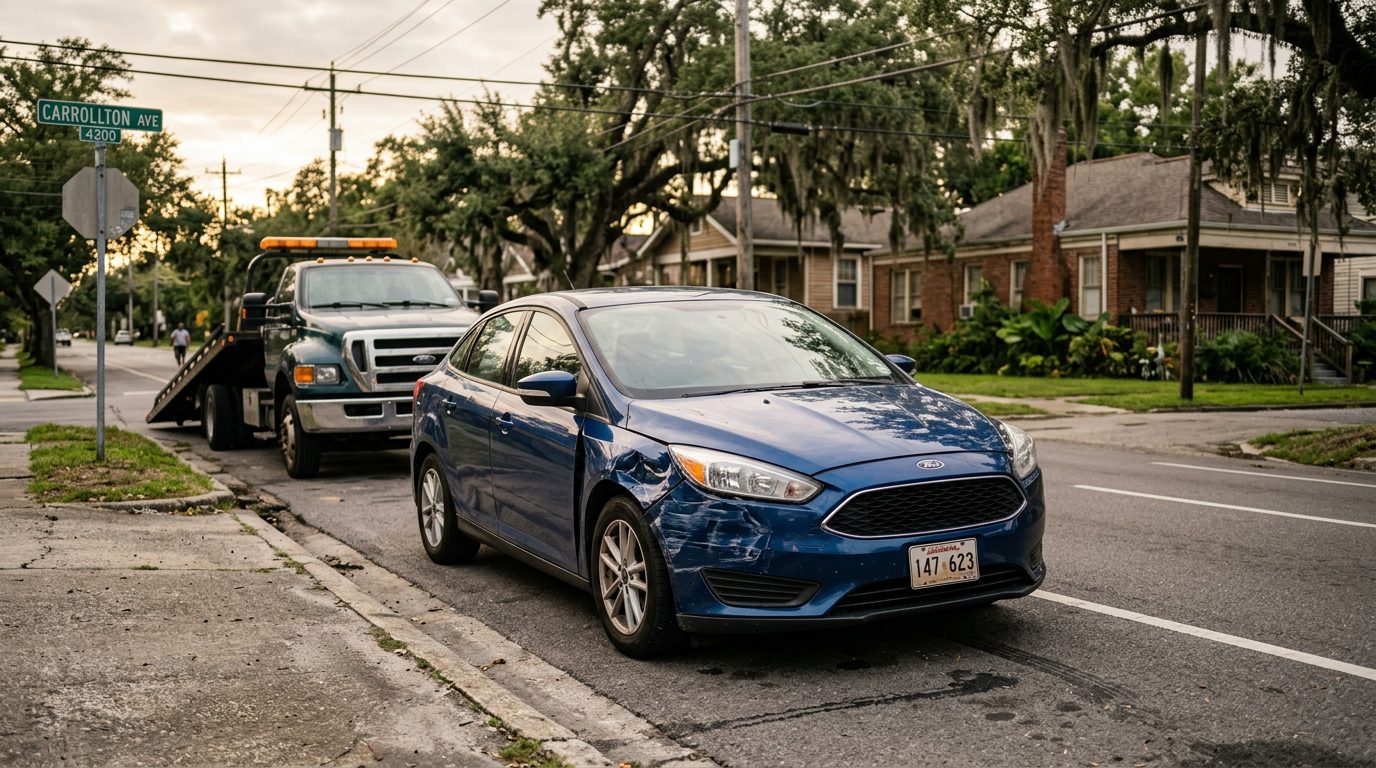
Car Accidents | New Orleans, Louisiana
Your Parked Car Was Hit and the Driver Has No Insurance? Let's Talk About Your Options.
A parked car is not always an unattended one. Here is how to protect your position and what a New Orleans trial lawyer can review with you.
By Przemek Lubecki · Published November 20, 2026
Coming home to a parked car with fresh damage is upsetting, especially when the other driver had no insurance or drove away. Generally, yes, you can sue the driver who hit your parked car, even if that driver is uninsured. Louisiana law says a person whose fault causes damage must repair it (La. Civ. Code art. 2315). The harder question is how the repair bill gets paid, and that depends on the facts.
Yes, you may have a claim against the driver
Yes, damage to your parked car can support a claim against the driver whose negligence caused it. Louisiana makes a person responsible for damage caused by negligence, imprudence, or want of skill, as La. Civ. Code art. 2316 states. Being uninsured does not erase that responsibility. It changes how the money is collected, and that is where most of the difficulty sits.
Under La. Civ. Code art. 2315, damages can include sales taxes you paid on the repair or replacement of the car.
Fault matters too. If your own negligence contributed to the damage, La. Civ. Code art. 2323 reduces your recovery in proportion to your share. For accidents on or after January 1, 2026, a share of 51 percent or more means no recovery.
If an uninsured driver left your parked car damaged, you may have a claim, and you don't have to sort out the insurance questions alone. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What happens when an uninsured driver hits a parked car
The driver may stay at the scene or leave, and no liability insurer will pay the repair bill when the driver has none.
Without a liability insurer, payment has to come from the driver personally or from your own coverage, if your policy includes it. Some owners only learn later that the driver was uninsured, which can change the next steps. If that happens, keep every record of the damage, including photos and repair estimates.
A common mistake is waiting for the other driver to make the first move. Details fade quickly, so write down what you saw while it’s still fresh.
Suing the uninsured driver for the damage
You can file a claim against the at-fault driver personally for the cost of repairs, plus any sales tax you paid on those repairs. Collecting from an individual with no insurance can be slow. A court judgment does not automatically mean the driver pays, so plan for that gap before you decide how to proceed. Keep copies of repair estimates, photos, and any messages with the driver, since they help show what the damage cost.
Small claims court handles smaller disputes, while higher courts handle larger ones. Which court fits depends on how much is in dispute. Ask yourself how much is at stake before choosing a path.
The firm may associate or refer a case to other law firms, and it will say so when that is likely.
Your own coverage: collision and uninsured motorist property damage
Your own policy may pay for the damage through collision coverage or uninsured motorist property damage coverage, depending on what you carry. Collision coverage, if you have it, pays for damage to your car under your policy’s terms and deductible.
Uninsured motorist property damage coverage works differently. Under La. R.S. 22:1295, if your auto liability policy does not include collision coverage for your car, the insurer must provide this coverage at the written request of a named insured on the policy, unless the named insured rejected uninsured motorist coverage. The amount is capped at the car’s actual cash value or the minimum property damage liability amount, whichever is less.
Where the conditions of La. R.S. 22:1295 apply, the uninsured motor vehicle property damage coverage described in that section is subject to a deductible of two hundred fifty dollars for any one accident. It does not protect against loss of use of the vehicle. Your own coverage and a claim against the driver can both be part of the plan, but uninsured motorist property damage coverage does not pay damages which are paid or payable under any other property insurance, so it helps to decide which path comes first.
Steps to take right after the damage and time limits to know
Document the damage and the scene first. Take photos of the car from several angles and of the surrounding area. Write down the location, the time, and where the car was parked. Note any witnesses and any nearby cameras.
If the other driver is present, get their name, address, and vehicle registration number. Under La. R.S. 32:398, and subject to the exceptions and conditions stated in that section, the driver of a vehicle involved in a crash resulting in injury to or death of any person, or property damage in excess of five hundred dollars, must give his name, address, and the registration number of the vehicle he was driving and, upon request and if available, exhibit his license or permit to drive to any person injured in the crash or to the driver or occupant of or person attending any vehicle or other property damaged in the crash.
Crash reports are confidential and are made available only to the parties to the crash, parents or guardians of a minor who is a party to the crash, insurers or an insurance support organization under contract to provide claims and underwriting for any party which is the subject of the report, healthcare providers that rendered healthcare services to any party which is the subject of the report, succession representatives of those parties, the attorneys of the parties or succession representatives, and news-gathering organizations requesting documents related to a specific crash. Under the same statute, upon request, crash reports are to be made available to the listed persons within seven working days following the completion of the crash investigation.
Louisiana generally sets a two-year time limit, called prescription, for these damage claims. Under art. 3493.1, it starts running from the day the damage is sustained, but it does not run against minors or interdicts in actions involving permanent disability brought under the Louisiana Products Liability Act or state product liability law. For claims under uninsured motorist policy provisions, La. R.S. 9:5629 also uses two years, counted from the accident date. Waiting can cost you the right to sue, so track that date from the start.
Talk with American Trial Lawyer about your parked car claim
Przemek Lubecki, a trial lawyer, is the responsible lawyer for this page, and the firm’s office is in New Orleans. The firm represents people in Louisiana car accident matters, including those in Orleans Parish, Metairie, Jefferson Parish, Kenner, St. Bernard Parish and Slidell.
You may be helping a parent or friend sort this out, or dealing with it for the first time yourself. Either way, the insurance questions can feel like a lot to handle at once.
Can I sue someone who hit my parked car without insurance?
Generally yes. You can bring a claim against the at-fault driver, even if that driver has no insurance.
Do I need to call the police?
Calling the police creates an official record of the damage, which can help if the other driver leaves or has no insurance.
Will hitting my parked car raise my insurance?
Whether a claim affects your rates depends on your policy and your insurer.
If an uninsured driver left your parked car damaged, you may have a claim, and you don’t have to sort out the insurance questions alone. Call 855-LUBECKI (our office is in New Orleans) or request a free case evaluation. The initial consultation is free, confidential, and without obligation to continue.
How Przemek Lubecki Can Help
Review your situation
We look at how the collision happened, what damage occurred and which coverage may be available to you.
Organize the evidence
We help gather photos, repair estimates, police reports and witness information that support your claim.
Explore every avenue
We examine all possible sources of recovery, including your own policy and claims against the at-fault driver.
Keep you informed
You will receive clear, plain-language updates and answers to your questions at every step.
Protect the Evidence
Photos of the damage, the location, and any visible license plate or vehicle details can help document what happened. A police report creates an official record, which can be valuable if the other driver leaves the scene or has no insurance.
Steps to Consider After a Parked Car Is Hit
Document the scene
Take wide and close-up photos of your vehicle, the surrounding area and any debris or marks on the street.
Get a police report
Ask responding officers to document the damage and the other vehicle, and request a copy of the report.
Notify your own insurer
Report the incident to your insurance company and ask what coverage applies when the other driver is uninsured.
Talk with a lawyer
Przemek Lubecki can review your facts and explain the questions to consider. The firm may associate or refer a case to other law firms, and we will tell you if that happens.